


Portugal continues to attract people looking for sunshine, lifestyle and security. But moving country can change the tax, regulatory and estate-planning context around pensions and investments. Arrangements that were suitable while living in the UK - or that were put in place several years ago - may no longer be the most appropriate, cost-effective or tax-efficient solution for someone resident in Portugal.
At OpesFidelio, we regularly meet expatriates who are unsure what their investments actually cost, whether their portfolio remains appropriate for their objectives, or how forthcoming UK inheritance tax changes could affect pension wealth. A cross-border review can help identify what needs attention - and, just as importantly, what does not need changing.
Understand What Your Investments Really Cost
Following Brexit, many UK expatriates moved to EU-compatible platforms, insurance-based investments or other cross-border structures. These can be entirely appropriate, but the overall cost can include several separate layers - for example fund charges, platform or product charges, adviser fees and, in some cases, legacy commission arrangements.
The important figure is not one individual charge but the total cost of ownership. Even a difference of 1% a year is €2,500 on a €250,000 portfolio before allowing for compounding. A review should therefore establish what you are paying, what you receive in return and whether lower-cost alternatives can meet the same objectives without sacrificing suitability or necessary cross-border features.
OpesFidelio advisers work on a transparent, disclosed remuneration basis so clients can understand the cost of the advice and investment solution before proceeding.
UK Pension IHT Changes Are Now Law
The UK pension inheritance tax reforms are no longer merely proposed. The Finance Act 2026 legislated for most unused UK pension funds and pension death benefits to be brought into the deceased member's estate for UK Inheritance Tax purposes for deaths on or after 6 April 2027.
That does not mean every pension will suffer 40% IHT. Whether tax is actually due depends on the value and composition of the estate, available allowances and exemptions, who receives the benefits and the individual's UK IHT position. Transfers to a surviving spouse or civil partner can remain exempt, and some benefits - including qualifying death-in-service benefits - are outside the new rules.
For British expatriates and others with UK pension wealth, this makes retirement and estate planning more connected than before. It may be sensible to review pension withdrawals, beneficiary nominations, other assets and succession plans together rather than treating the pension as a standalone investment. Any action should be based on individual tax and financial advice; moving or withdrawing pension money simply to avoid IHT can create other tax, investment and retirement-income consequences.
Portugal Has Changed Too: NHR Is No Longer the Default
Portugal's original Non-Habitual Resident (NHR) regime was repealed for new arrivals from 1 January 2024, subject to transitional rules for people who already qualified. Its successor, the Incentive for Scientific Research and Innovation (IFICI), is much narrower and is available only to people who meet specific residence and qualifying-activity conditions.
For people outside NHR or IFICI, Portuguese taxation of investments therefore matters directly when deciding how a portfolio should be structured. As a general rule, investment income and many securities gains are taxed at 28%, although the detailed treatment depends on the asset and circumstances. Since 2024, qualifying listed securities and units in open-ended collective investment undertakings held for more than two years may benefit from a partial exclusion from tax, increasing with the holding period. This makes investment structure, turnover and holding periods increasingly relevant to long-term planning in Portugal.
What Should a Cross-Border Review Cover?
• UK pensions and the impact of the IHT rules taking effect from 6 April 2027.
• The total cost of existing investments, including funds, platforms, products and advice.
• Portfolio risk, diversification and whether the investment strategy still matches your objectives and time horizon.
• Portuguese tax treatment of investments, including whether NHR transitional rules, IFICI or the ordinary tax regime applies to you.
• Beneficiary nominations, wills, succession planning and insurance needs.
• Whether existing UK or offshore products remain suitable for an EU/Portugal resident and whether any proposed change creates tax or exit-cost consequences.
The aim is not to change investments for the sake of it. A good review should identify where an existing arrangement remains suitable as well as where costs, tax treatment, risk or regulation justify a change.
The Time to Act Is Now
Markets move. Rules change. Costs compound. Reviewing your portfolio once every few years simply isn’t enough when you live and invest across borders.
By speaking with an independent, EU-regulated, UK-qualified adviser, you can:
- Cut unnecessary fund costs.
- Protect your family under new IHT rules.
- Optimise returns within compliant, transparent structures.
Your finances deserve the same attention as your lifestyle — secure, sustainable, and stress-free.
Why Cross-Border Expertise Matters
Cross-border advice is not simply about speaking English or having a local presence. It requires an understanding of where the client lives, where the assets and pensions are held, which regulatory permissions apply and when specialist tax or legal advice is needed.
Through the OpesFidelio network, clients can access appropriately regulated advice in relevant jurisdictions, together with advisers who understand UK pensions and the issues that commonly arise when people move between countries. This helps avoid looking at a Portuguese investment, a UK pension and an estate plan as three unrelated problems.
The Time to Review Is Before the Rules Change
The UK pension IHT rules take effect from 6 April 2027. For anyone in Portugal with significant UK pension or investment assets, the months ahead provide an opportunity to understand the position and consider whether any action is appropriate - without making rushed decisions close to the deadline.
A review should leave you with three clear answers: what you own, what it costs, and whether it remains appropriate for your life in Portugal.
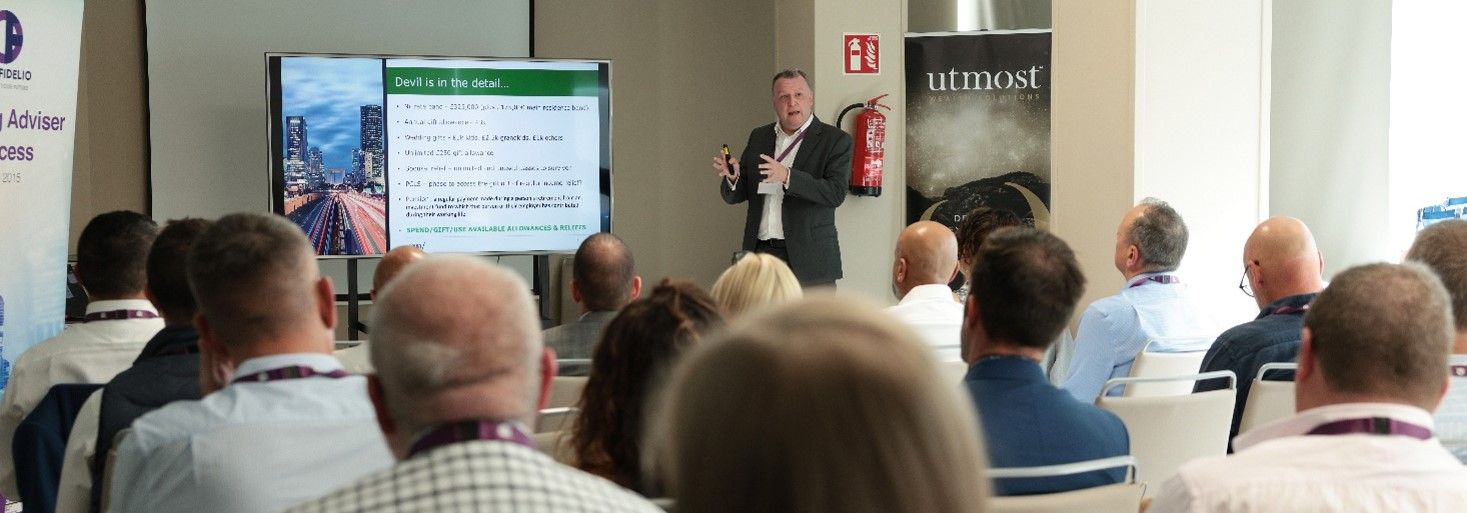
Upcoming Seminars – 27th & 29th October 2026
Meet our team of expert advisers and investment partners at our seminars this October - register today for your complimentary seat.
Speakers include:
James Pearcy-Caldwell, CEO of OpesFidelio
Simon Baker, Area Sales Manager (Europe) at Utmost
Nathan Sweeney, CIO of Marlborough
Paul Forman, International Sales Manager at Novia Global
Cascais - Tuesday 27 October 2026
6:30pm - 9pm
Hotel Baia
Passeio de D. Luís I, 2754-509 Cascais
Lagos - Thursday 29 October 2026
11am - 1pm
Boavista Golf & Spa
Quinta da Boavista, 8601-901 Lagos
Includes: Complimentary drinks and canapes
Email: admin@opesfidelio.eu
Tel: +351 300 600 990 (business hours)
Web: opesfidelio.eu/portugal26
Important Information
This article is for general information only and does not constitute personalised investment, tax or legal advice. Tax treatment depends on individual circumstances and can change. Where Portuguese or UK tax or legal advice is required, this should be obtained from an appropriately qualified professional. The value of investments can fall as well as rise and you may get back less than you invest.
OpesFidelio - Cross-Border Financial Advice
Transparent | Cross-Border | Client-Focused
Set The Portugal News as your preferred source for news on Google
 Add as a preferred source on Google






 Portugal Handbook
 English
 Nederlands
 Deutsch
 Français
 Español
 Italiano
 Svenska
 Pусский
 中文
 Türkçe
 Português
 Czech
 Hungarian
 Polski
 عربي
 Suomi
 עִברִית
 Português (Brasil)

Follow us on social media